
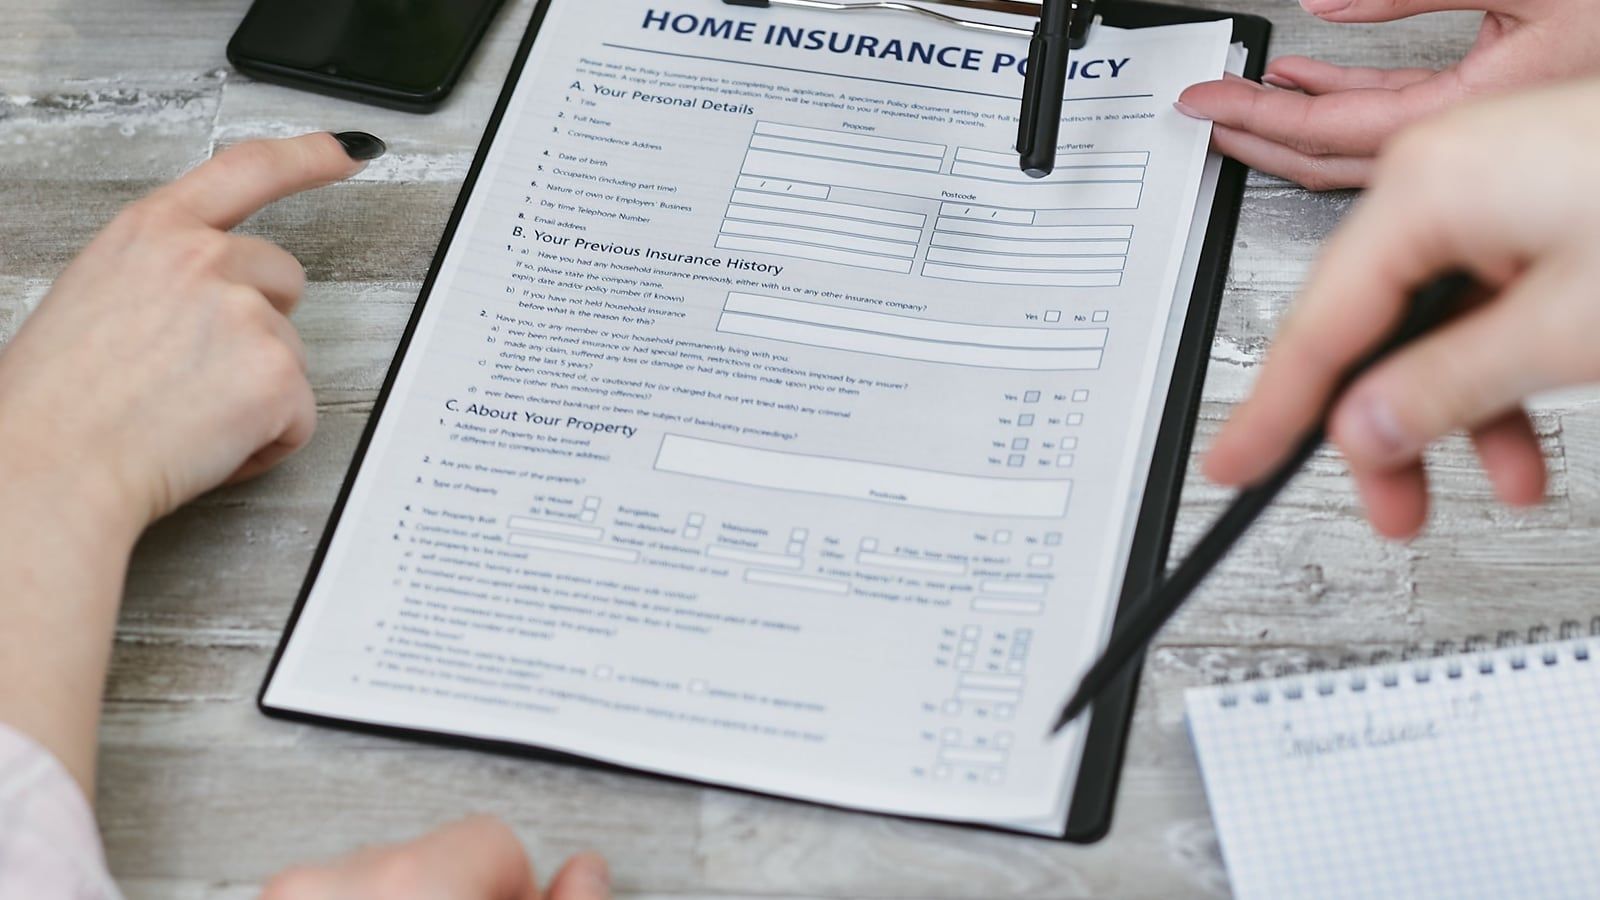
Do not wait until the final days before closing to shop for homeowners insurance on a Houston home. The annual premium is only the surface number; roof settlement terms, wind and hail deductibles, claim history, separate flood coverage, and remaining underwriting conditions can all change the real cost.
I recommend comparing the cash you may need after one serious loss before comparing a small difference in annual premium.
Why start during the option period?
A lender usually requires acceptable property insurance, but the buyer needs to confirm more than whether someone can issue a policy. If the quote still depends on roof records, an inspection, or additional photos, discovering a premium, deductible, or coverage problem late leaves very little time to investigate or negotiate.
Start after receiving the seller disclosure and early inspection information. Give the same property facts to each licensed insurance professional so you compare similar coverage—not a broader policy against a cheaper but thinner one.
First, correct one common myth about older roofs
In September 2026, the Texas Department of Insurance clarified that a company cannot decline or nonrenew a home policy solely because of the age of the house or roof. The physical condition of the roof and other systems may still affect underwriting. An older roof is therefore neither an automatic rejection nor a reason to skip condition review.
Ask three separate questions: Can the home be insured? How will the roof be paid after a covered loss? What deductible will apply?
A cheaper quote may differ in these six places
1. The quote may still require an inspection or documents
Ask whether the company still needs to verify roof age, plumbing, electrical, HVAC, or property photos. Is the number preliminary, or was it calculated using the specific home’s records? Do not treat an on-screen estimate as the final budget when key facts remain open.
2. Roof losses may pay replacement cost or depreciated value
TDI explains that some policies pay current repair or replacement cost, while others subtract depreciation based on age and condition. A lower premium does not necessarily mean less cash out of pocket after wind or hail damage. Ask about roof limitations, exclusions, and settlement method.
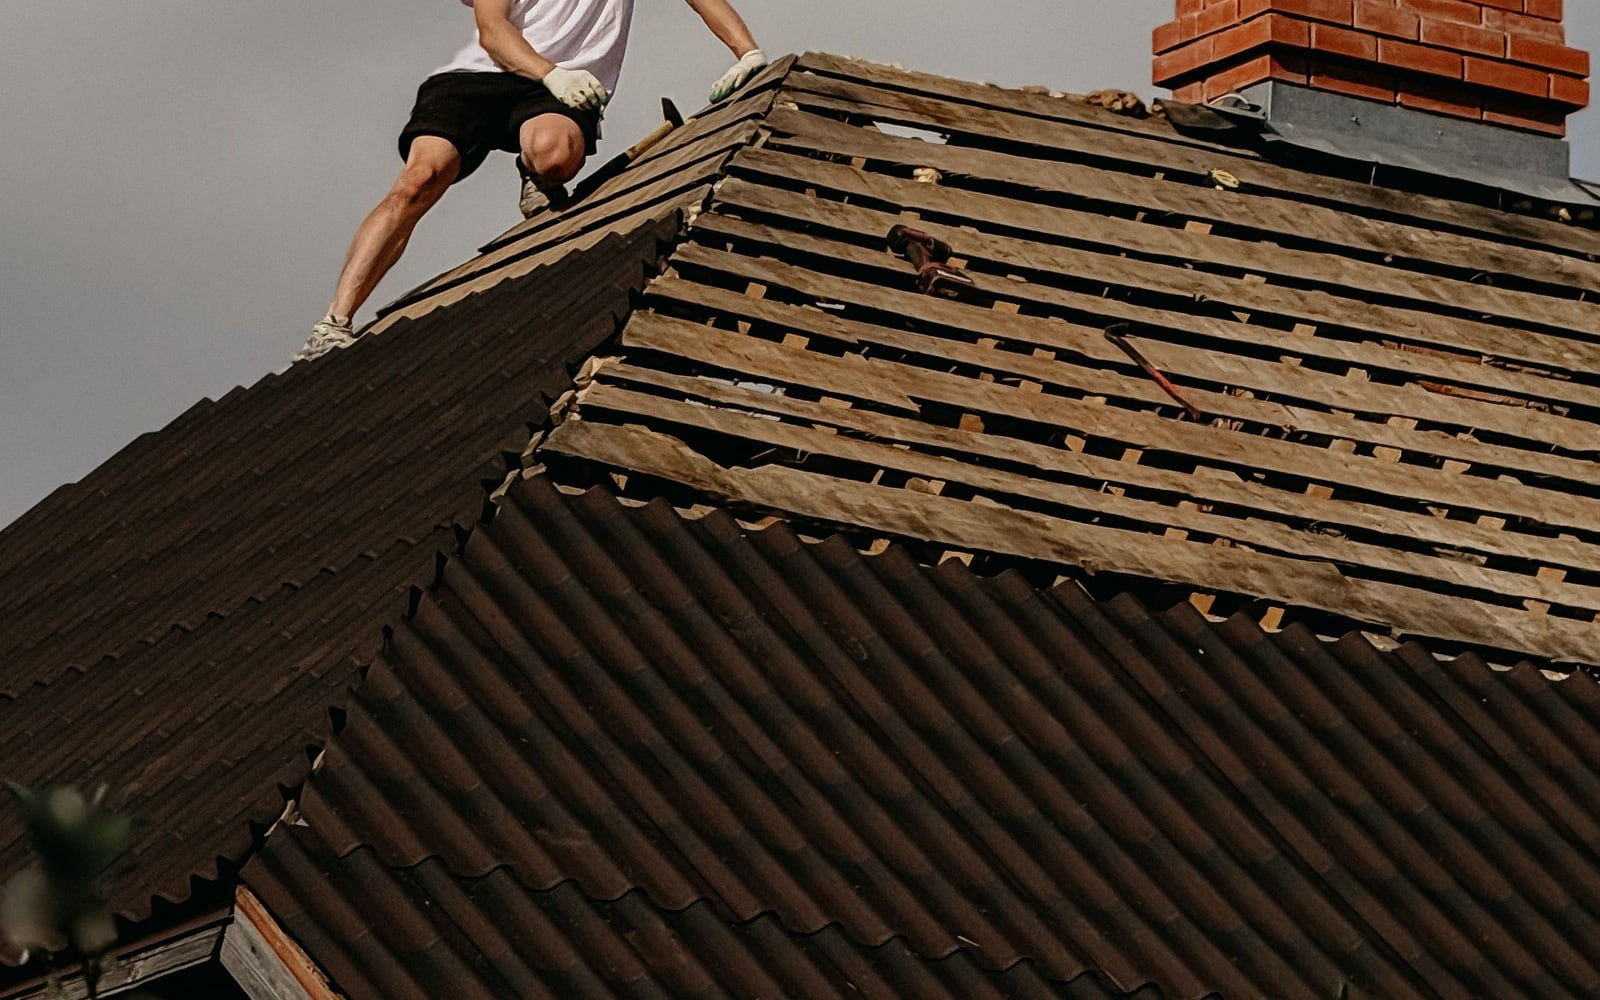
Real roof-work photo. Buyers should verify roof age, material, condition, and repair records. A photo does not replace an inspection or predict any insurer’s underwriting decision.
3. Convert the wind and hail deductible into dollars
Do not stop at “one percent” or “two percent.” Ask the insurance professional to identify the policy’s calculation base and state the deductible as a dollar amount. Compare the wind and hail deductible with the deductible for other covered losses.
4. Plumbing leaks, sewer backup, and flood are not the same event
TDI notes that most standard home policies do not cover natural flood damage; separate flood insurance is generally needed. Sudden interior leaks, long-term seepage, sewer backup, and surface water may be handled differently. Ask about the specific event instead of asking only whether “water damage” is covered.
5. The property’s seven-year claim history needs context
TDI says a CLUE report shows claims filed on a property during the past seven years, including the date, loss type, and amount paid. A buyer can ask the owner to provide it, then compare it with the seller disclosure, repair invoices, and inspection findings. A prior claim is not automatically a deal-breaker; unexplained damage or missing repair records are the larger concern.
6. A low premium may shift more risk back to you
Put the annual premium, dwelling limit, major exclusions, roof settlement, wind and hail deductible, other deductibles, and separately purchased coverage on one checklist. When two quotes differ sharply, identify the coverage difference before calling one cheaper.
What to do in the first 48 hours after contract
- Collect the address, year built, roof age, seller disclosure, and known repair documents.
- Request quotes early from two or three licensed insurance professionals using the same property information.
- Ask in writing about roof settlement, the wind and hail deductible in dollars, major exclusions, and outstanding underwriting conditions.
- Request the property’s CLUE report from the seller and compare claim events with repairs and inspection findings.
- Evaluate flood insurance separately for the specific address and risk; do not treat “outside the mandatory flood zone” as “no flood risk.”
- Add the annual premium and plausible high deductibles to the monthly-payment and cash-reserve plan.
If the home also has an older roof, HVAC, or other major systems, continue with What Buyers Should Prioritize During Inspection. To rebuild the full ownership budget, read Houston Homebuying Costs Beyond the Mortgage.
When should a buyer pause before ending the option period?
- The seller says the roof was replaced but cannot provide a date, invoice, or scope.
- The seller disclosure, claim history, and inspection findings do not align.
- The quote is low, but the roof pays depreciated value or the wind and hail deductible exceeds the buyer’s reserve.
- The insurer still requires inspection or repairs while the contract deadline is approaching.
- The property has a water history, but no one has separated flood, plumbing leaks, and sewer or drainage backup.
Pausing does not automatically mean terminating. It means identifying the facts that affect budget and closing before deciding whether to proceed, inspect further, or renegotiate.
Frequently asked questions
Why shop for insurance early if the loan is already preapproved?
Preapproval focuses on the borrower and preliminary loan terms; it does not confirm the cost or coverage for a specific property. The premium affects monthly housing expense, and insurance documentation may affect the loan process.
Will an insurer automatically reject an old roof?
Not solely because of age under TDI’s 2026 clarification. Physical condition may still affect eligibility, premium, and how roof losses are settled. Use the property records and actual quote rather than age alone.
If the seller disclosure says no flooding, can I skip flood insurance?
That conclusion is too broad. The disclosure reflects the seller’s knowledge. A flood-insurance decision should also consider the exact address, history, terrain, lender requirements, and the buyer’s risk tolerance. Standard home insurance generally does not replace flood insurance.
Who can provide the property’s CLUE report?
TDI says a buyer can ask the current owner to provide the report. Review it together with repair records and the inspection rather than treating claim count alone as the answer.
Joyce's Featured Listings
AI-generated illustration: a Greater Houston housing scene, not a real or currently available listing.
Screening insurance, roof condition, and flood exposure early gives you a more realistic price range than the mortgage payment alone. Browse Joyce’s Featured Listings, then verify coverage for each specific address.
View Joyce's Featured Listings →
Found a home but do not know what to ask the insurer?
Send me the address, seller disclosure, roof age, inspection summary, and any quotes you already have. I can help organize the missing property records, budget questions, and contract deadlines; a licensed insurance professional must confirm coverage and interpret the policy.
About Joyce Tang
Joyce Tang is a Greater Houston real estate agent and investor, co-founder of the North American Real Estate Association, founder of JoyHome and JoyNest, and co-leader of the Dr. Wang Real Estate Team.
She has helped more than 200 families buy or sell homes and has participated in more than 40 renovation projects. Her approach examines not only price, but also location, carrying cost, cash flow, risk and future exit options.
Sources and disclaimer
Sources checked October 17, 2026: TDI 2026 clarification on roof age and underwriting, TDI insurance and roof guidance, TDI CLUE report guidance, TDI questions before buying and insuring a home, the Texas home insurance guide, and the TREC Seller’s Disclosure Notice.
This article provides general real-estate and insurance-checklist information. It is not insurance, legal, lending, flood, or underwriting advice. Premiums, deductibles, coverage, and lender requirements depend on the property, applicant, insurer, and policy. Confirm them with the appropriate licensed professionals.
Cover photo from Pexels by Mikhail Nilov. Roof-work photo from Pexels by Bulat843 🌙. Both are used under the Pexels License. The images show general situations and do not represent a particular property, insurer, policy, or underwriting decision.