
A Houston homebuying budget should not stop at the price or the lender’s principal-and-interest payment. I separate the decision into three numbers: the true monthly housing cost, the cash needed at closing, and the reserves that must remain after you receive the keys. A home can qualify for financing and still strain the household budget if any one of those numbers is missing.
Start with three separate pools of money
- Ongoing monthly costs: principal and interest, mortgage insurance, property taxes, homeowners insurance, flood or wind coverage, HOA dues, and other applicable charges.
- Cash needed at closing: down payment, loan and title costs, prepaid insurance, initial escrow funding, less any eligible seller or lender credits.
- Post-closing reserves: moving, near-term repairs, insurance deductibles, furnishings, and unexpected expenses. This money should not automatically be pushed into a larger down payment.
Having enough for the down payment does not mean the home is affordable. The real test is whether household cash flow remains stable after closing.
Check at least eight parts of the monthly cost
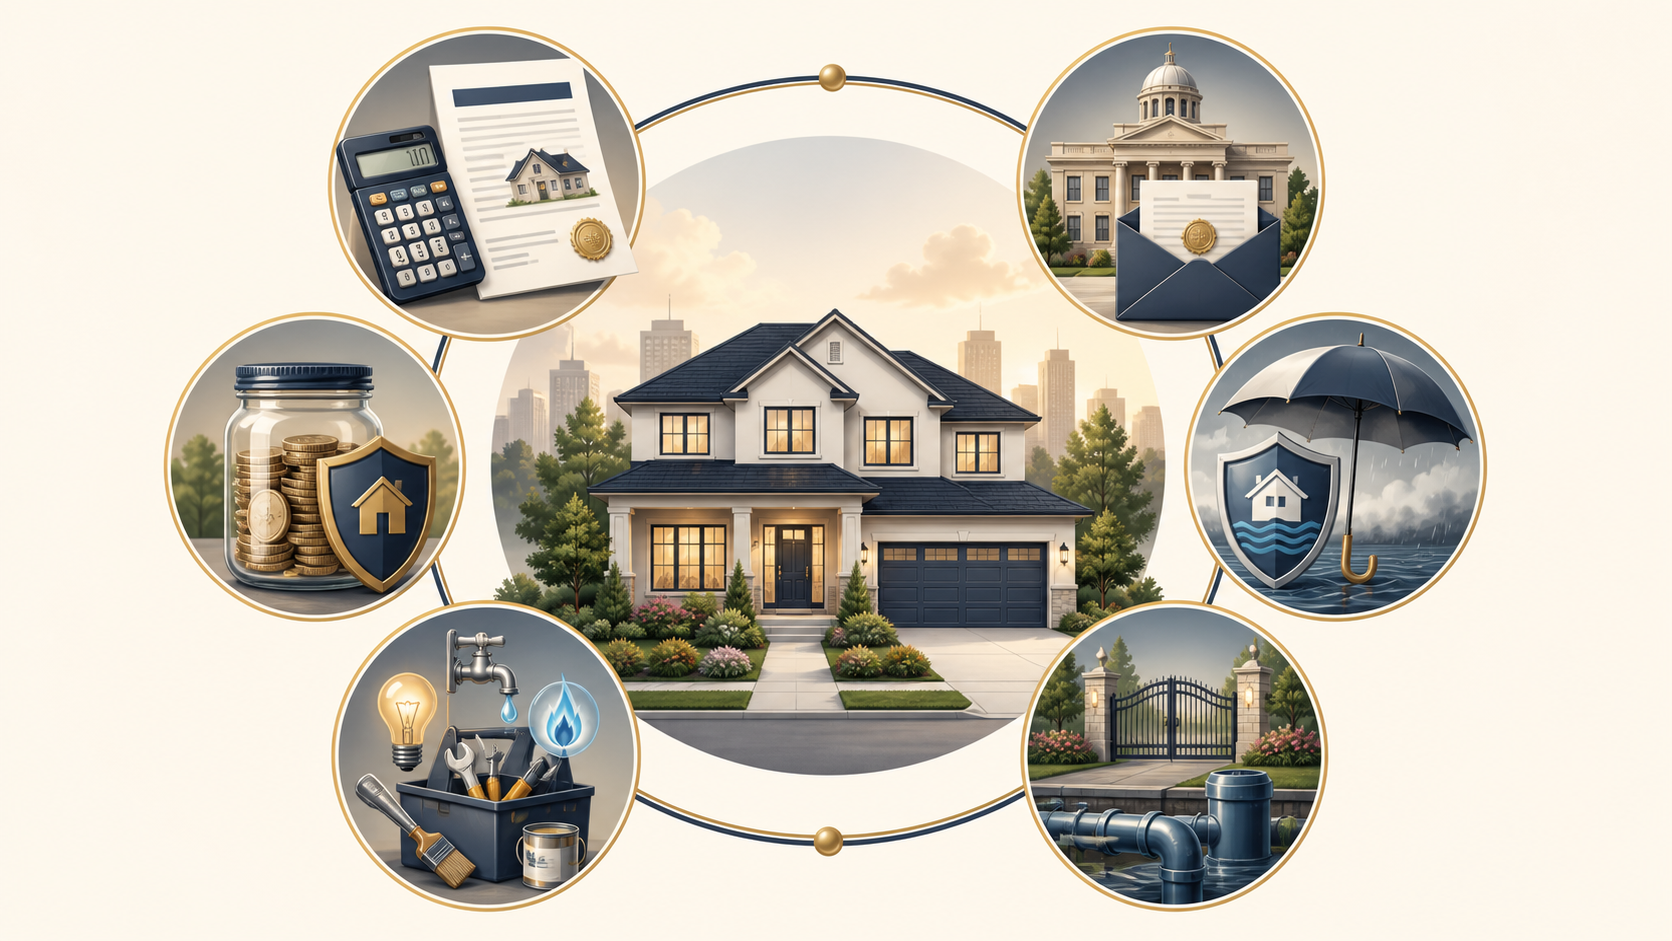
The graphic above separates the main layers of carrying a home. The exact mix changes with the address, property, and loan, but none of these numbers should be guessed.
- Principal and interest: the number most listing calculators emphasize, but only the first layer.
- Mortgage insurance: lower-down-payment loans may include PMI, MIP, or another program charge.
- Property taxes: estimate them for the exact address, taxable value, taxing units, and the buyer’s own exemption eligibility.
- Homeowners insurance: premium, covered losses, exclusions, and deductibles all matter.
- Flood or coastal wind coverage: standard home policies generally exclude flood; coastal properties may require a separate wind and hail review.
- HOA obligations: look beyond regular dues to transfer fees, special assessments, and rules.
- MUD or PID charges: MUD taxes may already appear in the tax bill, while PID assessments may be separate. Avoid both omissions and double counting.
- Utilities and maintenance reserves: these may be absent from the lender’s payment quote but still affect monthly cash flow.
Property taxes: do not copy the seller’s bill
Texas has no state property tax. Local taxing units assess and collect property taxes, and one Greater Houston address can involve a county, city, school district, MUD, or other special district. Two homes with the same price can therefore carry different monthly costs.
The seller’s tax bill is not necessarily the buyer’s future bill. The seller may have a residence homestead, age-based, or other exemption, along with historical appraisal limits that do not apply to the buyer in the same way. Eligible owners generally apply through the appraisal district for the county where the property is located. See the Texas Comptroller property-tax exemption guide.
I treat the tax number on a listing as a research starting point, not the final budget. New construction requires extra care because an early record may reflect land or an incomplete improvement rather than the finished home’s future taxable value.
Insurance: price, deductible, coverage, and insurability belong in one review
Insurance should not be a last-minute quote obtained only to satisfy closing. Roof age, property condition, claim history, coverage, and deductibles can change both the premium and the buyer’s real exposure after a loss. A lower premium paired with a large deductible may still create a difficult cash-flow risk.
The Texas Department of Insurance explains that a mortgage lender will generally require homeowners insurance, while standard home policies generally do not cover flood. Review the TDI home insurance guide and the TDI flood insurance guide.
Being outside a designated flood zone does not make the risk zero. For a specific address, ask separately about homeowners, flood, and—when relevant—wind or hail coverage.
Where buyers misread HOA, MUD, and PID costs
These are different obligations. An HOA governs a private community and collects dues. A municipal utility district, or MUD, can finance and provide water, sewer, drainage, or related infrastructure, with taxes that may already appear on the property-tax bill. A public improvement district, or PID, may fund roads, landscaping, or other improvements through an assessment.
Do not stop at asking whether one exists. Confirm the amount, payment schedule, whether it is already included in the tax bill, any special assessment, remaining term, and whether the charge can change. The controlling answers come from tax records, HOA documents, seller disclosures, title materials, and required notices for that property.
How much cash is needed at closing? The down payment is only one part
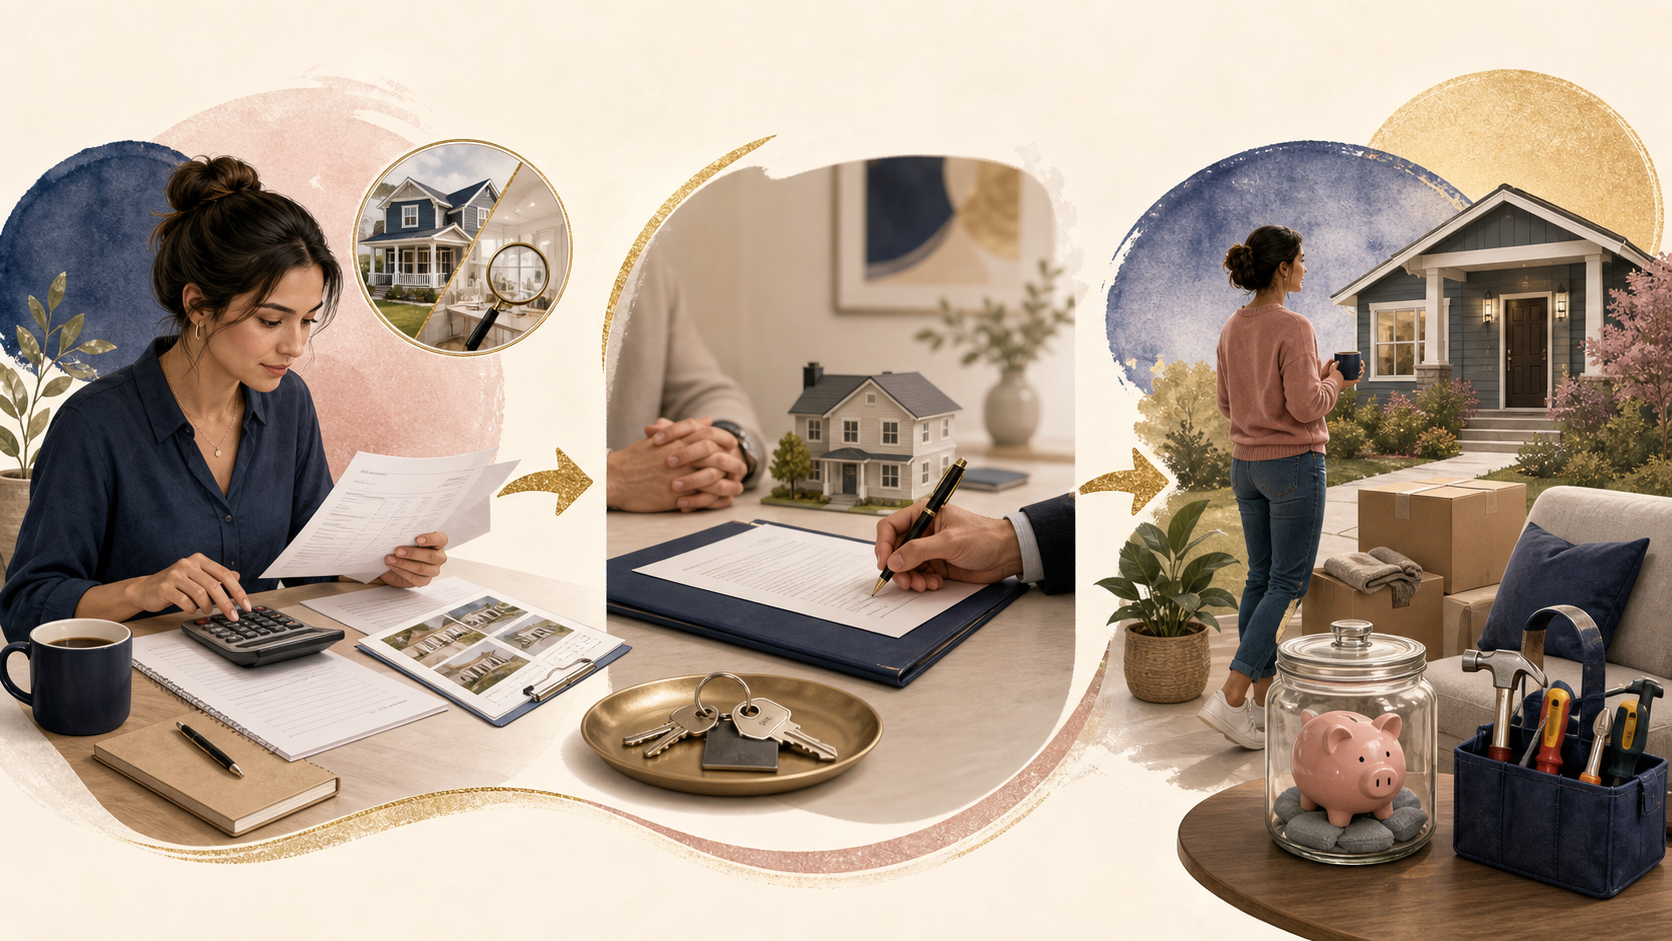
Cash planning may include the down payment, loan charges, title and recording costs, prepaid insurance, prepaid interest, and initial escrow funding. Inspection, appraisal, or other costs paid earlier should still be part of the complete purchase budget.
For early planning, the CFPB says closing costs commonly range from 2% to 5% of the purchase price, excluding the down payment, while actual costs depend on price, loan, location, and transaction details. Use that only as a first estimate, then replace it with the formal Loan Estimate. See the CFPB down-payment and closing-cost guide.
On the Loan Estimate, review the Estimated Total Monthly Payment, Estimated Closing Costs, and Estimated Cash to Close. When comparing lenders, keep the loan amount, term, rate-lock status, and points or credits consistent. The CFPB provides a detailed Loan Estimate explainer.
Seller concessions or lender credits can reduce the cash needed now, but they are not automatically free. A lender credit may be paired with a higher rate, and seller credits remain subject to loan rules, contract terms, and eligible costs. Compare the expected holding period, not only closing day.
How much should remain after closing?
There is no single percentage that fits every household. Home age, roof and HVAC condition, insurance deductibles, income stability, and planned improvements all change the reserve target.
I start with the expenses most likely to occur during the first year, then decide whether increasing the down payment still makes sense. If the roof, HVAC, water heater, pool, foundation, or drainage already shows risk, a generic maintenance percentage is not enough.
For a specific home, put these six items on one page
- A formal Loan Estimate, not only a verbal rate or online calculator.
- Address-specific tax records, taxing units, and a post-purchase estimate.
- Homeowners, flood, and—when relevant—wind coverage quotes.
- HOA dues, transfer fees, special assessments, and rules.
- MUD or PID notices, rates, remaining assessments, and payment schedules.
- Inspection findings, roof and HVAC age, and likely first-year repairs.
Putting those records side by side shows whether a home is actually less expensive or merely looks cheaper in the list price and first payment estimate.
A practical Houston homebuying budget formula
Total monthly cost = principal and interest + mortgage insurance + monthly property-tax estimate + monthly home/flood/wind insurance + HOA + applicable assessments not already counted in taxes + utilities and maintenance reserve.
Cash to close = down payment + closing costs + prepaids + initial escrow funding − eligible credits. Keep post-closing reserves separate.
If you are comparing new construction with resale, continue with Why Can a New Houston Home Cost Less Than a Resale? If the interest-rate environment is your main concern, read Why Is the Fed Discussing Rate Hikes When Mortgage Rates Are Already High?.
Frequently asked questions
Can I rely on the monthly payment shown on a listing site?
Not by itself. An automated estimate may omit or misstate taxes, insurance, HOA, MUD, or PID costs and may not reflect your credit, down payment, or loan. Recalculate for the address and actual financing.
The seller’s property tax is low. Will mine be the same?
Not necessarily. The seller may have different exemptions or historical appraisal limits. Budget using the buyer’s eligibility and a post-purchase estimate.
If a home is outside a flood zone, can I ignore flood insurance?
No. Standard homeowners insurance generally excludes flood, and flooding can occur outside designated zones. Check risk and pricing for the address.
Is a seller closing-cost credit always better than a price reduction?
No. A credit may reduce near-term cash more directly, while a price reduction affects the loan balance and long-term cost. Loan rules, eligible expenses, rate, and holding period all matter.
Joyce's Featured Listings
AI-generated illustration: a Greater Houston housing scene, not a real or currently available listing.
Once the budget is clear, browse Joyce’s Featured Listings to see current property types and price ranges, then narrow “qualifies on paper” to a home that fits both daily life and long-term cash flow.
View Joyce's Featured Listings →
Want to calculate the real cost of a specific home?
Send me the address, Loan Estimate, tax record, insurance quote, and HOA/MUD/PID information. I can help organize what may be missing, duplicated, or still needs confirmation before you decide whether to move forward.
About Joyce Tang
Joyce Tang is a Greater Houston real estate agent and investor, co-founder of the North American Real Estate Association, founder of JoyHome and JoyNest, and co-leader of the Dr. Wang Real Estate Team.
She has helped more than 200 families buy or sell homes and has participated in more than 40 renovation projects. Her approach examines not only price, but also location, carrying cost, cash flow, risk and future exit options.
Sources and disclaimer
This article is based on public information available in September 2026 from the Texas Comptroller, Texas Department of Insurance, and Consumer Financial Protection Bureau. It provides general real-estate information, not lending, insurance, tax, or legal advice. Confirm property-specific amounts, coverage, tax eligibility, and contract obligations with the lender, insurer, local appraisal district, title company, and appropriate licensed professionals.
Cover photo: Sasun Bughdaryan / Unsplash, cropped and used under the Unsplash License.