Houston housing costs moved in different directions this week. Rental demand remained resilient while average single-family rent was virtually flat; mortgage rates jumped; and Harris County adopted a higher combined tax rate. Buyers, landlords and investors should rerun their numbers rather than rely on last month’s payment or cash-flow assumptions.
My view: the most useful question is no longer simply whether home prices will fall or when rates will come down. Put the mortgage, property taxes, insurance, vacancy risk and available incentives on one page, then decide whether the specific property still works.
The week in one sentence
Houston rentals still have demand, but broad rent-growth power is limited; resale prices have not entered a new market-wide slide, but higher rates are making buyers more selective; builder incentives are larger, though heavily conditional; and the Harris County tax change means old escrow and investment assumptions need an update.
1. More single-family leases, but almost no rent growth
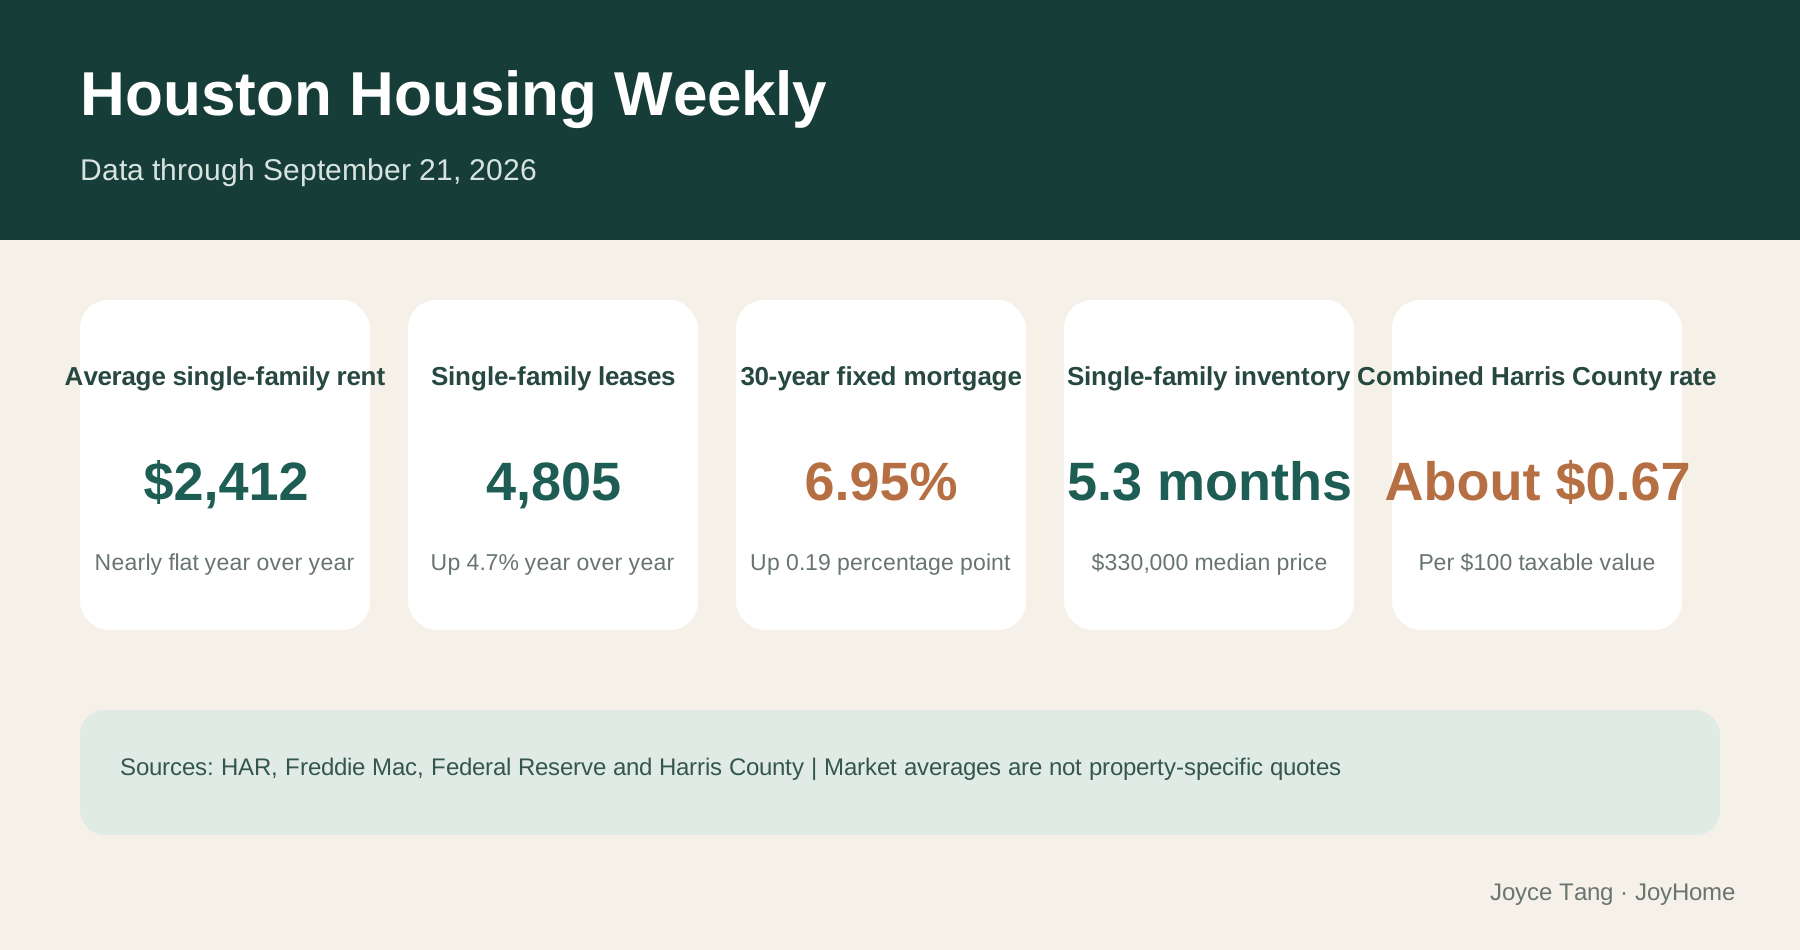
HAR’s August 2026 rental report, released September 16, showed 4,805 single-family leases, up 4.7% year over year. Average rent was $2,412 versus $2,414 one year earlier, and average market time increased by one day to 36 days. Read the HAR rental report.
That is not weak demand. More homes leased. The constraint is pricing power: renters have enough choice that landlords cannot assume healthy demand automatically supports a rent increase.
Townhome and condominium data were more mixed. Active rental inventory rose 9.0% and completed leases fell 2.7%, while average rent increased 2.4% to $2,014 and market time improved from 48 to 45 days. A higher metro average does not mean every community or floor plan can support a higher asking rent.
A landlord who holds out for an extra $100 per month but loses one month of rent would need roughly 24 months of that increase to recover a $2,412 vacancy loss.
What landlords should do this week
Compare the value of a reliable renewal with the full cost of turnover
Price new listings against comparable homes actually leased in the last 30 days, not only active asking prices
Include cleaning, repairs, leasing cost and vacancy days in the decision
For condos and townhomes, count direct competition within the same development or floor-plan group
2. Resale prices are not collapsing, but negotiation is becoming property-specific
There was no new monthly HAR sales report this week, so August remains the latest full benchmark: a $330,000 single-family median price, down 1.5% year over year; 5.3 months of inventory; 54 average days on market; and a 16.5% decline in sales between $500,000 and $999,999. Read the HAR market report.
A quiet open house or a few price reductions do not prove that the entire Houston market is falling again. Still, a sudden rate increase puts more pressure on homes with longer market time, higher total prices or condition problems.
A price cut is not the only seller tool. For a financed buyer, a closing-cost credit or permanent rate buydown may improve the payment more than the same nominal price reduction. A lender must calculate the option using the buyer’s loan type, down payment and seller-contribution limits.
For more context on the inventory-price disconnect, read Houston Inventory Hit a Record—So Why Haven’t Home Prices Fallen More?.
3. The 30-year average reached 6.95%, making older pre-approvals unreliable
On September 16, the Federal Reserve raised its federal funds target range by 0.25 percentage point to 3.75%–4.00%. Read the Federal Reserve statement.
Freddie Mac then reported a 6.95% average 30-year fixed mortgage rate as of September 17, up from 6.76% one week earlier. The 15-year average rose to 6.26% from 6.09%. See the Freddie Mac survey.
On a $400,000, 30-year fixed loan, principal and interest are approximately $2,597 per month at 6.76% and $2,648 at 6.95%—about $51 more. The change may look manageable by itself, but taxes, insurance, HOA dues and possible MUD or PID costs can push a borderline budget over its limit.
The Fed does not directly set 30-year mortgage rates, and 6.95% is a national average—not a guaranteed consumer quote. Credit, down payment, occupancy, loan type, points and lock period all matter.
What buyers should do this week
Update the pre-approval and full monthly payment using this week’s quote
Compare zero-point pricing, permanent buydowns and temporary buydowns using APR, cash due and five-year cost
Ask about lock periods and float-down terms without assuming a future refinance
Compare the home price, tax rate, insurance and seller incentives in one worksheet
For a deeper explanation, read The Fed’s First Rate Hike in Three Years: What Really Matters for Houston Mortgages.
4. Builder incentives are larger, but the headline maximum is not a cash promise
Bridgeland’s current incentive page lists up to $55,000 in flex savings and a 4.99% rate with 5.178% APR from Perry; up to $95,000 in flex spending on certain Newmark to-be-built Signature Series homes; up to $26,300 in features plus up to $10,000 in closing costs on certain Highland homes; and up to $25,000 in financing incentives on certain David Weekley purchases. Review Bridgeland builder incentives.
David Weekley also advertises waived lot premiums for eligible to-be-built homes in Prairieland Village–Summit Collection purchased September 3–30, with terms stating that the offer is not valid with every other promotion. Read the promotion terms.
When I review a builder promotion, I start with four questions: Which address qualifies? Is a preferred lender required? How many points are built into the advertised rate? What price would be available without the incentive?
Investors need extra caution because many advertised rates are designed for qualifying owner-occupants. Investment-property pricing, down payment and seller-contribution limits may be very different. Compare the five-year cash cost, not the largest number on the sign.
5. Harris County adopted the tax change—cash flow now needs an address-level update
On September 17, Harris County Commissioners Court adopted the FY2027 budget and related tax rates. The combined rate across Harris County, Harris Health, Port Houston and the Flood Control District is about $0.67 per $100 of taxable value. County officials estimated roughly $198 more for the average homeowner this year. Review Harris County budget documents and
The $198 figure is an estimate, not a fixed increase for every property. Actual bills depend on taxable value, exemptions and other taxing entities such as the city, school district and MUD. A Fort Bend or Montgomery County property cannot use the Harris County figure.
What owners and investors should do this week
Rerun Harris County investment cash flow, including insurance and HOA assumptions—not only county tax
Leave room for the next escrow analysis without guessing the payment change from an average estimate
For a pending purchase, pull every taxing entity by the property’s tax account rather than copying the seller’s prior payment
Do not assume a landlord can automatically pass the new tax cost to a tenant; rent is still limited by the property’s competitive set
My overall read on the Houston market this week
Houston is not one simple buyer’s market or seller’s market. Buyers have more leverage in parts of the resale and new-home market, but financing and ownership costs absorb some of that benefit. Landlords can still find tenants, but broad rent growth is limited. Sellers may have room to offer help, but the concession should solve the buyer’s actual financing problem.
The practical move this week is not to predict the next headline. Replace old inputs with current ones: refresh the loan quote, verify the exact tax jurisdiction, price from recent closed or leased comparables, and convert every builder or seller incentive into a monthly payment and five-year cost.
Frequently asked questions
If the national mortgage average is 6.95%, should my quote also be 6.95%?
No. Freddie Mac reports a national average. Your quote depends on credit, down payment, occupancy, loan type, points and lock period. Compare rate, APR, fees and cash due together.
Can Houston landlords still raise rent?
It depends on the community and property type. Metro-wide single-family average rent was nearly flat year over year, so broad pricing power is limited. Compare the real cost of a stable renewal with potential vacancy.
Does a $50,000 builder incentive automatically beat a resale home?
No. Confirm the eligible address, stacking rules, lender requirement, lot premium, upgrade cost, tax rate and five-year ownership cost. A resale home may offer a different mix of price, repairs and tax basis.
Will every Harris County homeowner pay $198 more?
No. That is the county’s average estimate. The actual change depends on taxable value, exemptions and every taxing entity attached to the property.
View current listings
Listing status, pricing and incentives can change quickly. To compare this market update with properties that are currently available, visit the JoyHome listings page for active residential, land and commercial opportunities.
View the latest JoyHome listings
About Joyce Tang
Joyce Tang is a Greater Houston real estate agent and investor, co-founder of the North American Real Estate Association, founder of JoyHome and JoyNest, and co-leader of the Dr. Wang Real Estate Team.
She has helped more than 200 families buy or sell homes and has participated in more than 40 renovation projects. Her approach examines not only price, but also location, carrying cost, cash flow, risk and future exit options.
If you are buying, selling or reevaluating a rental property, send me the address, budget, down payment, expected holding period and current loan quote. We can compare the payment, taxes, insurance, incentives and exit options on one page.
Sources and disclaimer
Data are current through September 21, 2026, and come primarily from HAR, the Federal Reserve, Freddie Mac, Harris County and public builder promotion pages. Market data, rates, taxes and incentives can change; verify transaction-specific terms in current written documents.
This article is for general real estate and market education only. It is not lending, tax, legal or investment advice and does not guarantee rent, price, rate, incentive or cash-flow results. Consult a licensed lender for loan terms and qualified tax or legal professionals for those matters.
Written by Joyce Tang|Serving Greater Houston, Texas.