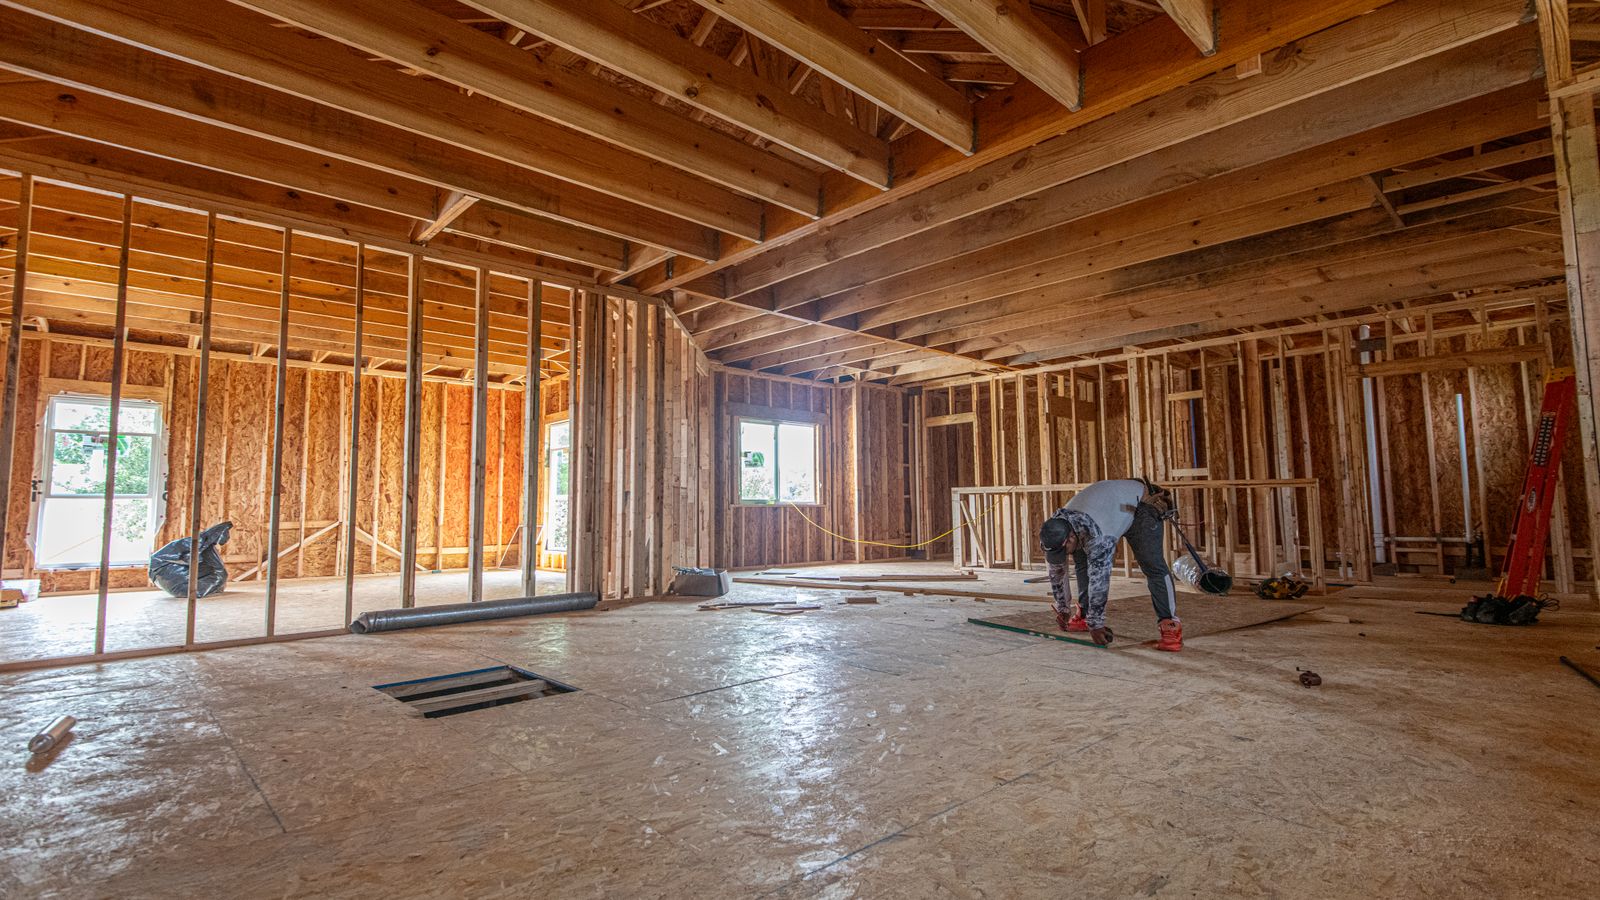
A promotional rate, closing-cost credit or upgrade package does not automatically make a new home a good deal. Buyers often overpay not because they received nothing, but because they focused on the one number the builder wanted them to see.
I evaluate a builder offer through four separate costs: the contract price, the full monthly payment, the property itself and future resale. An incentive is valuable only when all four still make sense.
Why big incentives are so persuasive right now
As of September 21, 2026, the average 30-year fixed mortgage rate was 6.95%. Greater Houston had 5.3 months of single-family inventory, and August sales were down 11.5% from a year earlier. Nationally, 66% of builders were using sales incentives and 38% had cut prices.
Builders have more reason to negotiate, but pressure is not equal across communities or homes. A low advertised rate or large credit is not the same as money saved.
Why are these incentives easier to negotiate now?
The underlying logic is straightforward. Higher rates push some buyers to wait and price others out of financing. Buyers who are fully qualified, clear about their terms and able to close on schedule become more valuable because certainty itself is scarce.
Land, construction, labor and financing costs are already embedded in a completed home, and carrying pressure continues each month it remains unsold.
When several similar inventory homes compete in one community, a buyer can compare the builder's own homes against one another instead of negotiating only one address.
To protect community pricing, a builder may adjust rate support, closing costs, upgrades, appliances or lot premiums before making a large base-price cut.
When an offer becomes tied to a particular home and closing date—or previously separate incentives can be combined—the builder is trading terms for a more certain closing.
This does not mean every completed home is negotiable or that month-end and quarter-end always produce the biggest discount. It means leverage is specific to the community, the home and the buyer's ability to perform. A softer market creates the opening; preparation turns it into written terms.
Cost 1: Is the incentive built back into the contract price?
A builder can package value as a price reduction, rate buydown, closing credit, appliance package or upgrade allowance. Those options are not financially equivalent. A lower payment may leave the price unchanged, and an upgrade allowance may not return its full cost at resale.
Compare the contract price with recent community sales, other inventory homes and relevant resales.
Separate lot premiums, upgrades, appliances, title-related charges and other add-ons.
Ask what price or credit is available without the promotional financing.
Consider whether the contract price creates appraisal risk.
Cost 2: How long does the low payment last?
The sales office may highlight principal and interest, but your housing budget also includes property taxes, homeowners insurance, homeowners-association dues and special-district charges.
Confirm whether a rate buydown is temporary or permanent. If the payment rises after one or two years, can the budget still carry it? A future refinance should never be treated as guaranteed.
Compare at least three Loan Estimates: the builder-lender rate offer, a builder-lender option using funds toward other closing costs, and an outside-lender offer. Review rate, annual percentage rate, points, cash to close, payment during the incentive and payment afterward.
Cost 3: Is this the right house, even without the incentive?
The most heavily promoted home may simply be the one the builder wants to move first. That can be harmless—perhaps it is complete or one of several identical plans—but it can also reflect lot position, road exposure, drainage, noise or nearby construction.
I separate the house from the promotion. First decide whether the property makes sense without the incentive. Then decide whether the incentive fairly compensates for any tradeoff.
Review lot position, orientation, rear exposure, roads and planned development.
Verify taxes, special districts, association rules and insurance estimates.
Hire an independent inspector; new does not mean unchecked.
Document construction items, the punch list and warranty responsibilities.
Cost 4: Who will compete with you when you resell?
Today the builder can offer a subsidized rate, a warranty and brand-new inventory. If the community is still building when you sell, your resale may compete with those same advantages.
Look at remaining lots, future supply of similar floor plans, taxes that affect the next buyer's payment, and any obvious resale weakness. Today's incentive matters, but so does tomorrow's exit.
Why asking only for the lowest price misses the point
The builder can move money among several buckets. The goal is not to maximize every bucket; it is to maximize the one that solves your problem. A buyer short on closing cash may value a credit. A long-term owner may prefer price or a permanent buydown. A buyer likely to move sooner should pay closer attention to resale.
A sales office can explain its homes. It cannot compare the whole market for you.
The onsite salesperson works to complete sales for the builder. They may know the community extremely well, but their role is not to compare your budget across competing builders, communities and resales.
That is the value of a buyer's own agent: applying one standard across the market and turning different incentive packages into an apples-to-apples decision.
Working with me is not about having one more person at the model home
The sales office explains why the home is attractive. I help you decide whether it is worth buying.
Screen communities by total monthly budget, not list price alone.
Identify inventory homes, returned contracts and competing floor plans.
Normalize written offers from different builders.
Prioritize price, rate or closing cash based on your holding plan.
Coordinate independent inspection, insurance quotes, contract milestones and closing preparation.
Consider rental, resale and future competition before you commit.
Planning to tour Houston new construction? Send me these five items first.
Purchase budget and expected down payment
Maximum total monthly housing cost
Work location, commute needs or target areas
Preferred move-in or closing timeline
Communities or home links you are already considering
I can start with a new-construction offer comparison that puts contract price, financing, cash to close, taxes, insurance and long-term carrying cost in one view. Then we can decide which community—and which home—is worth negotiating first.
Contact me before your first sales-office visit or online registration when possible so we can confirm that community's registration and broker-cooperation rules. Buyer representation, scope of service and compensation should be explained and agreed to in writing as required.
Frequently asked questions
Can I tour the sales office first and hire an agent later?
You can, but builders may have their own first-visit registration and broker-cooperation policies. It is better to confirm those rules before visiting or registering online.
Is the builder's low rate always better than a price reduction?
No. Compare the buydown term, annual percentage rate, points, cash to close, expected holding period and whether the lower rate comes with a higher contract price.
Does a new home still need an independent inspection?
Yes. New construction can still have workmanship, installation, drainage or punch-list issues. A builder warranty does not replace a pre-closing inspection.
Will having my own agent increase the new-home price?
Builder pricing, incentives and broker-cooperation policies vary. Buyer representation and compensation should be understood in advance, while the decision should focus on the transaction's net cost, risk and long-term value.
Data sources
Federal Reserve statement, September 16, 2026; Freddie Mac mortgage-rate survey, September 17, 2026; NAHB builder survey, September 2026; and HAR August 2026 Houston housing report.
Related reading
Why Can a Houston New Home Cost Less Than a Resale Right Now?; Buying a Home in Houston: What Costs Come Beyond the Mortgage Payment?; and Houston Inventory Hit a Record—So Why Haven't Home Prices Fallen More?.
Disclaimer: This article uses information available as of September 21, 2026 and is for general educational and homebuying purposes only. It is not lending, tax, legal or investment advice. Mortgage rates, builder incentives, loan qualifications, contribution limits, buyer-agent compensation and inventory can change. Verify current terms in written contracts, loan documents, builder policies and with appropriate licensed professionals.
About Joyce Tang
Joyce Tang is a Greater Houston real estate agent and investor, co-founder of the North American Real Estate Association, founder of JoyHome and JoyNest, and co-leader of the Dr. Wang Real Estate Team.
She has helped more than 200 families buy or sell homes and has participated in more than 40 renovation projects. Her approach examines not only price, but also location, carrying cost, cash flow, risk and future exit options.